The short answer: Paying off a Dubai mortgage early, or moving it to another UAE bank, costs money up front: an early settlement fee that the Central Bank caps at 1% of the balance or AED 10,000, whichever is lower, plus Dubai Land Department (DLD) registration and the new bank’s costs. It pays off only if your monthly saving covers all of that within the time you expect to keep the loan.
This guide is for people who already hold a residential mortgage from a UAE bank on Dubai property. The Central Bank can change its rules, and banks set their own fees and offers. Check the current text and each bank’s written figures before you act. This is general information, not mortgage advice.
1. Your options, in plain terms
| Option | What it means | Main cost to check |
|---|---|---|
| Pay off in full | You clear the balance from savings or a sale | Early settlement fee, plus a small DLD release fee |
| Pay part early | You reduce the balance but keep the loan | Whether your bank charges a fee on partial payments |
| Switch to another bank (a buyout) | A new bank pays off your old loan and you owe the new bank | Settlement fee, DLD registration, valuation and the new bank’s fees |
| Stay, but ask your bank to reprice | You keep the loan and ask for a better rate or product | Any fee the bank charges to change terms: ask in writing |
A buyout does not change the property’s owner, so it is not a sale. Only the lender changes.
2. What the rules say about the fee
Two Central Bank texts matter, and they describe the charge differently:
- Consumer-loan regulation (No. 29/2011). The Central Bank’s rulebook lists the early settlement fee on a home loan as at most 1% of the outstanding balance or AED 10,000, whichever is less. The same rule applies to moving a loan to another UAE bank or finance company. The cap came in after a 2019 reduction from 3%.
- Mortgage regulation. The Central Bank’s mortgage rulebook says borrowers must be free to refinance, and that charges to refinance or repay early are limited to the lender’s actual cost of breaking a fixed-rate loan plus fees allowed under the consumer-loan regulation.
Three practical points:
- A cap is a maximum, not a default. Ask the bank to show how it calculated your figure.
- Check whether your loan is fixed or variable. A fixed-rate period may have a different break cost. Ask which rule your bank applies and get the amount in writing.
- Check for a waiver. Some banks advertise fee waivers for buyouts. These change often, so confirm the terms and end date at the time you apply.
We could not open the Central Bank rulebook pages directly during this review (access was refused), so the 1% and AED 10,000 figure comes from search-result excerpts of the rulebook and 2019 news reports. A reviewer should confirm it against the current text.
3. The full cost stack of a buyout

| Cost | What we know | Source and note |
|---|---|---|
| Early settlement fee (old bank) | Capped at 1% of the balance or AED 10,000, whichever is lower | Central Bank rulebook; confirm current text |
| DLD mortgage transfer | 0.25% of the mortgage value, plus AED 250 for the title deed and AED 10 knowledge and AED 10 innovation fees per drawing | DLD mortgage transfer page, accessed 20 Nov 2026 |
| DLD service partner fee | AED 4,000 plus VAT if you use a trustee centre (AED 5,000 plus VAT for an Oqood-registered unit). When the bank files online, DLD fees are taken from the bank’s account | Same DLD page |
| DLD mortgage release | AED 1,000, plus AED 250 for the title deed certificate and AED 10 plus AED 10 per drawing; service partner fee AED 300 plus VAT | DLD mortgage release page, accessed 20 Nov 2026 |
| Valuation | Set by the new bank; sources give different amounts and some banks absorb it | Ask for it in writing |
| Arrangement, processing, insurance | Vary by bank and offer | Ask both banks for a written cost sheet |
Ask whether your lender requires home insurance and whether your current policy carries over. Our guide to property insurance in the UAE explains the cover.
Depending on how your two banks structure the switch, DLD may record a mortgage transfer or a release followed by a new registration. Your banks will tell you which applies. The example below counts both to stay cautious.
There is no 4% sale registration fee, because ownership does not change. The DLD mortgage transfer page lists 0.25% of the mortgage value, not the 4% sale fee.
4. The break-even check: a worked example
The numbers below are an illustration built on assumptions. The rates are not market quotes, and the valuation fee is an assumed figure.
Assumptions: AED 1,000,000 balance remaining; 20 years left; current rate 5.5% and a new offer at 4.5% (both illustrative); reducing-balance repayments; early settlement fee at the AED 10,000 cap; valuation AED 3,000 assumed; no arrangement fee; VAT on service fees ignored.
| Line | Amount |
|---|---|
| Monthly payment at 5.5% over 20 years | About AED 6,879 |
| Monthly payment at 4.5% over 20 years | About AED 6,326 |
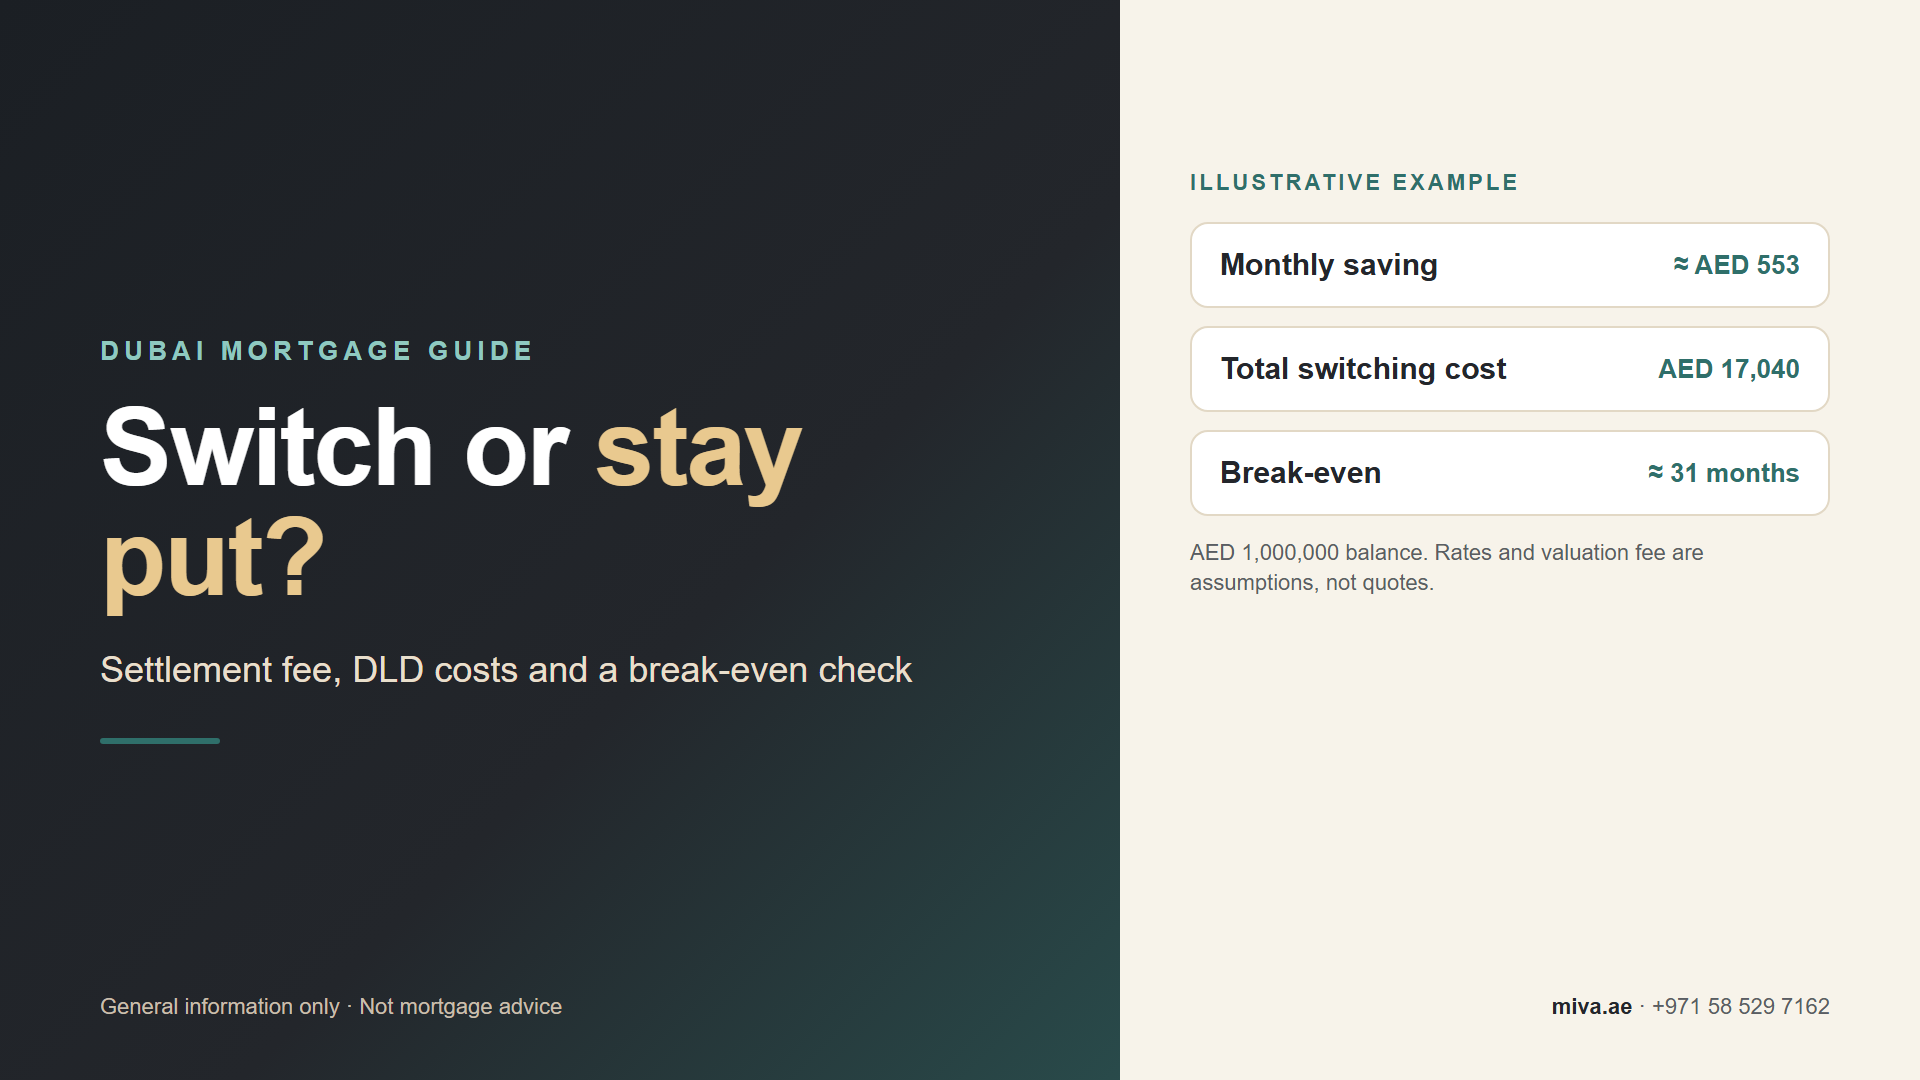
| Monthly saving | About AED 553 |
| Early settlement fee (cap) | AED 10,000 |
| DLD mortgage registration: 0.25% (AED 2,500) + AED 250 + AED 20 | AED 2,770 |
| DLD release: AED 1,000 + AED 250 + AED 20 | AED 1,270 |
| Valuation (assumed) | AED 3,000 |
| Total switching cost | AED 17,040 |
| Break-even: AED 17,040 ÷ AED 553 | About 31 months |

Read the result carefully. If you keep the new loan for more than about 31 months and the rate stays as assumed, the saving beats the cost. If you plan to sell or pay off within two years, it does not. A fixed rate that ends and resets can also change the picture, so model the rate after the fixed period. Use our guide to using a Dubai mortgage calculator for the repayment maths.
5. When switching does not make sense
- Little time left or a short stay. A short remaining term or a planned sale leaves too little time to recover the costs.
- A small rate gap. A saving of a few dirhams a month rarely covers the fee.
- The new bank may say no. It must run its own valuation and affordability checks. The Central Bank limits the loan to a share of the appraised value, so if your property is valued lower than before you may be asked to put in cash, or be declined.
- Fixed-period break costs. Leaving a fixed period early can cost more than the headline cap suggests. Ask for the written figure first.
- Fees can move the answer. A fee waiver can bring break-even down sharply, and a higher valuation or arrangement fee can push it up.

6. How a buyout works, step by step

- Ask your current bank for a written settlement figure and its fee.
- Apply to the new bank and give it your documents.
- The new bank values the property and issues its offer.
- The banks and, where needed, a trustee centre complete the DLD registration. DLD lists about 15 to 20 minutes for the transfer step and 10 to 15 for a release.
- Your old mortgage is closed and you pay the new bank.
Timelines quoted by brokers run from a few weeks to a couple of months. They depend on the banks and on documents, so treat them as indicative. For what a trustee centre does and when a lawyer adds value, see our guide: Do You Need a Lawyer to Buy Property in Dubai?
7. Paying off or paying part: what to ask
Before you use savings, ask your bank in writing:
- Is there a fee on a full or a partial payment, and how is it calculated?
- Does a partial payment shorten the term or lower the monthly amount?
- Is there a limit on how often or how much I can prepay?
- What happens to any fixed rate I am on?
Then weigh the saving against the cash you give up. Paying off a loan can reduce your interest, but it also removes cash you may want to keep for other needs. If you want help comparing written offers, our mortgage service can introduce you to qualified advisers and lenders.
8. Miva’s view: pros, cons and who it suits
Pros of switching
A lower rate or a better product can reduce your monthly payment. A written break-even check shows the real cost before you commit.
Cons
Upfront costs, a new valuation and a fresh approval. The saving is not guaranteed and rates can change. Not worth it if you will sell or settle soon.
Who it suits
Owners who expect to keep the loan well beyond the break-even point and whose property value and income still meet current lending rules. Not a substitute for a lender’s written offer.
9. Your checklist before you switch or settle
- I have my current rate, balance and remaining term in writing.
- I asked my bank for the settlement figure and how it was calculated.
- I know whether my rate is fixed or variable and when it ends.
- I have a written cost sheet from the new bank, including valuation and fees.
- I added the DLD fees and calculated the break-even in months.
- I checked how long I plan to keep the property.
- I have confirmed the new bank’s approval before I give notice to my current bank.
Need help comparing your options?
We can introduce you to qualified mortgage advisers and lenders so you can compare written offers. Miva does not lend and cannot guarantee approval or rates. You can also contact our team.
Frequently asked questions
1. What is the early settlement fee on a mortgage in Dubai?
The Central Bank’s rulebook lists a maximum of 1% of the outstanding balance or AED 10,000, whichever is lower, for home loans. Banks may charge less. Ask your bank for the exact amount in writing.
2. Can I switch my mortgage to another bank in the UAE?
Yes. The Central Bank’s mortgage rules say borrowers must be free to refinance with another institution. The new bank must approve you and value the property.
3. How much does a mortgage buyout cost in Dubai?
There is no single figure. Costs include the early settlement fee, DLD registration of 0.25% of the mortgage value plus fixed fees, a valuation and any bank charges. Ask both banks for a written cost sheet and work out the break-even.
4. Is it worth switching for a 1% lower rate?
It can be, if you keep the loan long enough. In our illustrative example on a AED 1 million balance, a one-point cut broke even in about 31 months. Your result depends on your costs and rates.
5. Do I pay the 4% DLD fee when I switch banks?
No. The 4% fee applies to a sale. DLD’s mortgage transfer page lists 0.25% of the mortgage value plus fixed fees.
6. Can non-residents switch their mortgage?
Some lenders consider non-residents, but terms and documents differ by bank. Ask each bank for its policy in writing.